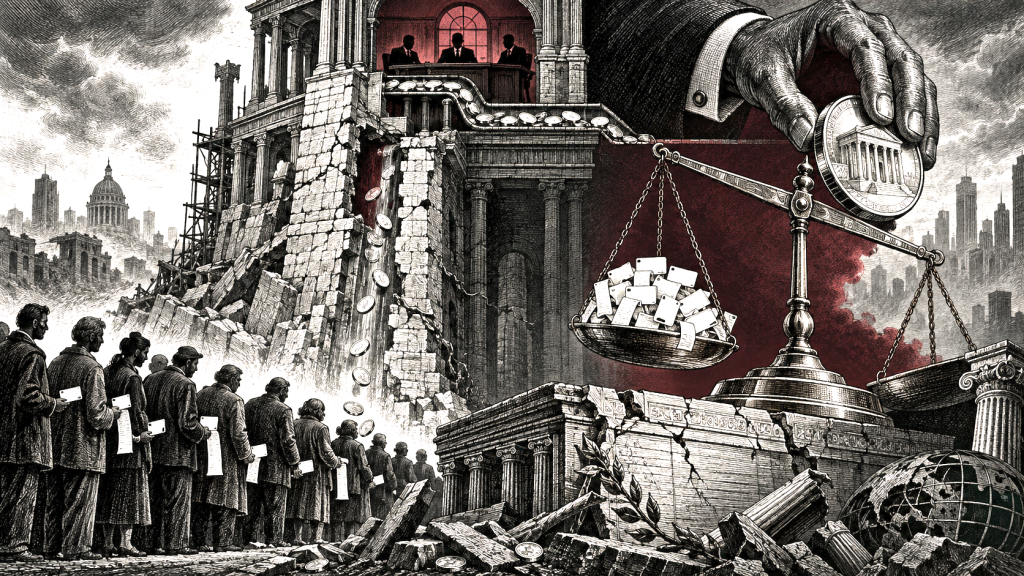
By Boo Kok Chuon When True Fitness and True Yoga ceased operations across their Singapore outlets on 10 September 2026, some customers discovered that what they thought they had purchased was not merely a gym membership. In insolvency, the unused portion of a prepaid package becomes, in substance, unsecured credit extended to the operator. One
By Boo Kok Chuon
When True Fitness and True Yoga ceased operations across their Singapore outlets on 10 September 2026, some customers discovered that what they thought they had purchased was not merely a gym membership. In insolvency, the unused portion of a prepaid package becomes, in substance, unsecured credit extended to the operator.
One customer told Shin Min Daily News that he had bought “Lifetime Founder VIP” memberships for himself and his two daughters in 2014, spending about S$21,000 in total, and still paid an annual fee of S$107. Another said she had paid about S$10,000 for a lifetime membership in 2020. By the evening of 11 September 2026, the Consumers Association of Singapore had received 241 complaints involving more than S$609,000 in reported losses from unutilised memberships, packages and services. That figure had risen from 28 complaints and S$63,000 earlier the same day, and is likely to keep moving.
These customers had no security, no interest, no financial covenants and no access to management accounts. They did not decide how the business would be capitalised. Most probably did not understand themselves to be creditors at all. They believed that they were buying future services.
At the same time, the unaudited management figures published through the operators’ Hong Kong-listed parent, Kontafarma China Holdings Limited, disclosed a very different creditor relationship. As at 31 August 2026, the True Singapore Group had approximately HK$204.5 million in assets, HK$633.8 million in liabilities and HK$429.3 million in net liabilities. Of those liabilities, approximately HK$309.7 million, or roughly S$50 million, was owed to the Kontafarma group.
If the parent group’s claim is ultimately admitted as an ordinary unsecured debt, Singapore insolvency law appears capable of placing it in the same residual pool as customers claiming for prepaid but undelivered services.
Formally, both are unsecured creditors. Economically, they could hardly be more different.
This article does not suggest that the Kontafarma group’s claim is invalid, that the financing was improper, or that it ought necessarily to be subordinated. The final amount owing will be determined in the liquidation. The published figures aggregate True Fitness Pte Ltd and True Yoga Pte Ltd, and do not disclose what would be required to reconstruct the position of each legal entity or to calculate an actual liquidation dividend.
But the figures expose a larger question that deserves examination:
Should Singapore insolvency law invariably treat uninformed, non-controlling credit as equivalent to informed, controller-linked credit, or should our courts possess a limited jurisdiction to examine whether some shareholder financing was debt in name but equity in substance?
Where the liquidation actually stands
Precision matters here, because the procedural posture affects who can ask the court for anything.
The directors of True Fitness Pte Ltd and True Yoga Pte Ltd resolved on 10 September 2026 that the companies could not continue their business by reason of their liabilities. Goh Wee Teck and Lin Yueh Hung of RSM SG Corporate Advisory were appointed provisional liquidators. Extraordinary general meetings of both companies are scheduled for 7 October 2026, at which resolutions for creditors’ voluntary winding up are to be proposed, with creditors’ meetings to follow.
That sequence corresponds to the route in section 161 of the Insolvency, Restructuring and Dissolution Act 2018 (IRDA): a statutory declaration by the directors that the company cannot by reason of its liabilities continue its business, immediate appointment of a licensed insolvency practitioner as provisional liquidator, and meetings of the company and of its creditors summoned for a date within 30 days after the date of the declaration. This is a voluntary winding up, not a winding up by the court. If the proposed winding ups proceed, adjudication of proofs of debt will ultimately fall to the liquidators, and any recovery will depend on assets realised and the statutory order of priority.
Two further facts matter for the analysis that follows. First, these are two separate estates, not one. Press reports citing Bloomberg put accumulated losses at roughly S$82.8 million for True Yoga and about S$13.5 million for True Fitness as at the end of 2025, so the aggregate group figures say little about either company’s individual position. Second, the parent has guaranteed a bank loan taken by the Singapore fitness business, with about S$2.3 million reported as outstanding at the date of the announcement. If a guarantor pays out, it may in principle acquire its own claim against the estate by subrogation or indemnity, subject to the rule against double proof, which prevents two proofs in respect of what is in substance the same debt.
What the published figures tell us, and what they do not
The first discipline is arithmetic.
| Reported position as at 31 August 2026 | HK$ million |
|---|---|
| Total assets | 204.5 |
| Total liabilities | 633.8 |
| Net liabilities | 429.3 |
| Amount owed to Kontafarma group | 309.7 |
| Liabilities excluding the parent-group balance | 324.1 |
| Net liabilities excluding the parent-group balance | 119.6 |
The amount reportedly owed to the parent group constituted approximately 48.9% of total liabilities. On the face of the aggregated figures, reported assets covered only about 32.3% of all liabilities. If the parent-group balance were removed purely as an analytical counterfactual, book asset coverage of the remaining liabilities would rise to approximately 63.1%.
The True Singapore Group would still have been balance-sheet insolvent on that simplified adjustment. Its adjusted net liabilities would remain approximately HK$119.6 million. The parent balance therefore does not create the insolvency by itself.
The trajectory is also instructive. At 31 December 2025, the reported position was assets of about HK$149.7 million against liabilities of about HK$555.5 million, giving net liabilities of about HK$405.8 million, on revenue of HK$181.2 million and a loss of HK$34.3 million. Over the following eight months, reported liabilities grew by about HK$78.3 million and reported assets by about HK$54.8 million, while the recorded loss was HK$19.1 million on revenue of HK$118.4 million. A business sustaining continuing losses and expanding net liabilities must finance the resulting cash requirements somehow. Kontafarma stated expressly that it had provided cash funding to support the Singapore fitness business.
Classification of that funding matters enormously to external creditors. Let A represent the assets actually available for distribution to ordinary unsecured creditors, after secured claims, realisation costs, liquidation expenses and the debts given priority by section 203 of the IRDA, which include employee wages, retrenchment benefits and CPF contributions, each within its own statutory category, period and prescribed limit. Let E represent admitted external unsecured claims and P the admitted parent-group claim. Equal ranking produces:
R (pari passu) = A ÷ (E + P)
If some or all of the parent claim were instead subordinated, the theoretical first-level recovery of external creditors becomes:
R (external) = the lesser of A ÷ E, or 1
This is not a prediction of recovery in these liquidations. A is not the same as total accounting assets, and on these facts the gap is likely to be wide: staff were terminated abruptly, and qualifying employee claims, including wages and CPF contributions, subject to the statutory categories, periods and limits, will rank ahead of ordinary unsecured creditors. Landlords have already repossessed premises. Nor do the published figures tell us the terms, timing, purpose or composition of the HK$309.7 million balance, or how it is split between the two companies.
But the model demonstrates why ranking is not a metaphysical argument. Classification determines who absorbs loss.
The orthodox Singapore position
Singapore insolvency law begins from a sensible premise: debt does not cease being debt merely because the creditor is a shareholder.
The point arose in Lim Oon Kuin and others v Ocean Tankers (Pte) Ltd (interim judicial managers appointed) [2021] SGCA 100; [2022] 1 SLR 434. That was an appeal against summary judgment on a claim for breach of directors’ duties, concerning two payments totalling about US$19.02 million made by Ocean Tankers to accounts connected to the Lims in April 2020. Mr Lim Oon Kuin argued that the payments were made in exercise of his rights as a creditor, that he had supported the company with unsecured and interest-free loans amounting to approximately US$225 million as at 31 March 2020, and that such shareholder’s loans ought properly to be regarded as equity in the company’s balance sheets.
That last submission was the appellants’ argument, not the court’s conclusion. The Court of Appeal agreed with the judge below that the shareholder’s loans would nevertheless be considered debts in the context of insolvency, and would at the least be contingent liabilities relevant to the balance sheet test, citing Kon Yin Tong and another v Leow Boon Cher and others [2011] SGHC 228 at [39]–[40]. The court added that the Lims’ own defence had averred that the loans were repayable on demand and that Mr Lim had all the rights of a creditor to recall them.
The distinction is crucial, and it cuts against the easy assumption. An accounting or economic resemblance to equity does not, under the present law, deprive a shareholder advance of its legal character as debt. The argument in Ocean Tankers illustrates the tension starkly: the advances were characterised as equity when their treatment as liabilities affected solvency, but invoked as debt when repayment was defended as the exercise of creditor rights.
The IRDA prescribes the statutory priorities in a winding up. Section 172, which applies to every voluntary winding up and so to the mode proposed here, requires that, subject to the provisions as to preferential payments, the property of a company be applied pari passu in satisfaction of its liabilities. Section 203 sets out the debts that are to be paid in priority to all other unsecured debts. There is no general category providing that a genuine shareholder loan ranks behind ordinary unsecured creditors merely because the lender owns or controls the borrower.
The legislation does distinguish sums due to a person in that person’s character as a member. Section 121(1)(g) provides that a sum due to any member in that member’s character of a member, by way of dividends, profits or otherwise, is not a debt of the company payable to that member in a case of competition with a creditor who is not a member. But an ordinary loan made by a shareholder is conceptually different: the shareholder claims as creditor, not as member.
Singapore courts also give effect to contractual subordination. Parties may agree that shareholder or related-party financing will not be repaid until specified senior liabilities have been discharged. In BCBC Singapore Pte Ltd and another v PT Bayan Resources TBK and another [2023] SGCA(I) 1, a subordination letter recorded the order in which the joint venture vehicle was to repay a project loan facility and two shareholder loan agreements, making full repayment of the facility a condition precedent to the accrual of payment obligations under the shareholder loans. The court analysed the parties’ rights by reference to that agreed ordering, albeit in the setting of a contractual and damages dispute rather than a distribution in liquidation. The principle is nonetheless clear: this is subordination by bargain, not a court demoting a claim because it belongs to an insider.
Our law is considerably more suspicious when the issue is not the existence of insider debt, but what controllers did with it as insolvency approached.
Chee Yoh Chuang and another (as Liquidators of Progen Engineering Pte Ltd (in liquidation)) v Progen Holdings Ltd [2010] SGCA 31; [2010] 4 SLR 1089 is directly on point, and it is an unfair preference case rather than a subordination case. The subsidiary’s audited accounts recorded the S$18.5 million owing to its sole shareholder and holding company as a non-current liability, and Note 13 stated that the amount was non-trade, unsecured, interest-free and not expected to be repaid within the next twelve months. A directors’ statement issued with those accounts represented that the holding company had agreed to fund the subsidiary and to subordinate the amounts owing to it and its related companies for the prior payment of other liabilities.
Economically, those features strongly resembled quasi-capital, although the court neither recharacterised nor subordinated the underlying debt. In fact, S$10,987,960.85 had already been paid to the holding company weeks before the assurances were issued, and the balance was extinguished within months, while two arbitration awards in favour of unrelated creditors went unpaid. The Court of Appeal held that the breach of those assurances fortified rather than rebutted the statutory presumption of a desire to prefer. The court’s opening observation was that priority payments benefiting related parties will ordinarily attract judicial scepticism, and more so where creditors outside the group, whose claims rank equally, are left with nothing.
Progen therefore contained many of the factual features that a classification inquiry would examine. The remedy available was nonetheless avoidance of the preferential repayment, not reclassification of the underlying advance. The case was decided under the unfair preference provisions of the Companies Act and Bankruptcy Act then in force, but those provisions were carried into the IRDA in substance, and the connected-person presumption survives in section 225(5). Nothing in the consolidation created a power to recharacterise or subordinate that the earlier regime lacked.
Alongside the avoidance provisions in Part 9 of the IRDA, which include presumptions where the counterparty is connected with the company, directors may breach their duties where they cause a financially imperilled company to favour related parties at the expense of the general body of creditors.
But avoidance and subordination answer different questions.
Avoidance asks whether a payment or transaction should be reversed and returned to the estate. Equitable subordination asks where a creditor’s claim should rank after it has been admitted. Recharacterisation asks an anterior question: was the supposed debt, in commercial substance, really risk capital from the beginning?
The present Singapore position may therefore be summarised this way:
We police how insiders exercise creditor rights, but generally do not question the priority conferred by creditor status itself.
Pari passu: equality between whom?
The pari passu principle is foundational. Subject to security, statutory preferences, set-off and other recognised exceptions, similarly situated unsecured creditors share rateably. It promotes collective distribution and prevents a disorderly race in which the swiftest or best-connected creditor captures the remaining assets.
The Court of Appeal’s decision in DGJ v Ocean Tankers (Pte) Ltd (in liquidation) and another appeal [2024] SGCA 57; [2024] 2 SLR 790 illustrates how seriously that principle is taken. A debtor of the company procured the assignment of claims to itself in the advent of the company’s compulsory liquidation, intending to assert an insolvency set-off. The court held that the assignments were ineffective and the set-off unavailable, refusing to allow the collective distribution regime to be subverted by an arrangement conferring an artificial advantage on one party.
But equal treatment depends upon a prior act of classification. Pari passu does not tell us which claims ought to enter the same class; it tells us how claims already treated as equal should share.
That is where the True Fitness figures make the orthodox position uncomfortable.
A prepaid customer generally lacks access to financial statements, cash-flow forecasts and board deliberations. She cannot impose covenants, negotiate security or alter the debtor’s capital structure. She may not know that her prepayment provides interest-free working capital until the contracted services are delivered.
A controlling parent occupies a fundamentally different position. It may have continuing access to financial information. It may influence directors, strategy, distributions and the timing of additional funding. Most importantly, it may choose whether money enters its subsidiary as ordinary shares, shareholder debt, secured debt or some hybrid instrument.
The distinction is not simply consumer versus corporation. Nor is it weak creditor versus powerful creditor. The analytically useful contrast is:
uninformed, non-controller credit versus informed, controller-linked credit.
Both creditors may contract voluntarily. But only one ordinarily understands, monitors and may help structure the insolvency risk.
Borrowing the logic of DLOC
Valuation professionals routinely recognise that control has economic value.
A discount for lack of control, or DLOC, reflects the reduced value of an interest where its holder cannot direct corporate policy, determine distributions, appoint management, initiate transactions or otherwise influence outcomes. The precise application of DLOC is contested and fact-sensitive, but its underlying economic insight is familiar: two nominally similar interests need not have the same value where one carries control and the other does not.
DLOC is not an insolvency doctrine. It does not determine statutory priority, and it should not be smuggled into legal analysis as though it does.
It nevertheless supplies a useful analytical lens. If corporate finance and valuation recognise control as economically valuable before insolvency, why should the informational and decision-making advantages attached to control become wholly invisible when insolvency distributes loss?
The analogy is inverted. In valuation, the absence of control may justify a discount to value. In insolvency, the presence of control may justify heightened scrutiny of a controller’s claim. Not because control is wrongdoing, but because it affects the creditor’s ability to understand, price and shape the risk that external creditors must bear.
Three variables matter:
- Control. Could the creditor influence the debtor’s affairs or capital structure?
- Information. Did the creditor possess materially superior knowledge of the debtor’s financial position?
- Structuring power. Could the creditor decide whether its contribution took the legal form of debt or equity?
A passive minority shareholder who makes a bona fide loan is not equivalent to a parent company controlling the borrower outright. Relationship alone should never decide priority. But control, information and structuring power may justify asking whether the legal label faithfully reflects the underlying bargain.
They do not answer that question by themselves, and they do not answer it in the same way for each remedy. Control and information do not transform debt into equity. A fully informed parent can make a completely genuine commercial loan. For recharacterisation, these factors explain why the insider’s chosen label warrants scrutiny, but the ultimate inquiry remains whether the financing possessed the commercial substance of debt at inception: repayment expectation, maturity, return, permanence, undercapitalisation and whether an independent lender would have advanced it. For equitable subordination, control becomes more directly relevant, because the question there is whether it was used to obtain an unfair advantage or to prejudice outsiders.
Debt capital or risk capital?
Consider two companies funded with the same HK$300 million.
Company A receives HK$300 million in ordinary equity. Upon insolvency, the shareholder bears the entrepreneurial loss before creditors.
Company B receives HK$1 in ordinary equity and HK$299,999,999 through a shareholder loan. If the loan ranks as ordinary unsecured debt, the shareholder may compete with suppliers and customers for the residual assets.
Corporate law ordinarily permits both structures. Debt and equity have different tax, governance, return and risk consequences. A shareholder does not lose freedom of contract merely by controlling the borrower.
But the economic distinction can become vanishingly thin where the purported loan has no meaningful maturity, attracts no commercially explicable return, is never enforced, rolls over indefinitely, funds permanent operations, depends for repayment upon the success of the business, and would not plausibly have been advanced by an independent lender on comparable terms. The Progen accounts recorded several of those features on their face: non-trade, unsecured, interest-free, not expected to be repaid within twelve months.
At some point, insolvency law may legitimately ask whether the money was advanced because the contributor expected repayment as a creditor, or because the business required risk capital that its owner chose to dress in debt clothing.
That inquiry is not an attack on separate legal personality. Respecting a company’s distinct personality does not compel a court to accept every label attached by controllers to a financial contribution. The issue is not whether the shareholder and company are the same person. It is whether the company’s obligation has been classified according to its commercial substance.
Two different remedies for two different problems
Recharacterisation and equitable subordination are often spoken of together, but they should not be conflated.
Recharacterisation treats a purported loan as a capital contribution because it was substantively equity from inception. The transaction did not possess the substantial commercial characteristics of debt.
Equitable subordination accepts that the claim is genuine debt, but postpones its ranking because particular conduct or circumstances make equal participation unjust. The remedy is directed at priority, usually only to the extent necessary to correct the prejudice.
Suppose a parent lends to a well-capitalised subsidiary on genuine commercial terms. Years later, when insolvency becomes likely, the parent abuses its control to obtain an unfair advantage over external creditors. Calling the original loan equity would be analytically false. If the law requires a ranking remedy, equitable subordination is the more precise instrument.
The United States expressly recognises equitable subordination under §510(c) of the Bankruptcy Code. American courts do not subordinate all insider debt categorically. Insider status commonly attracts closer scrutiny, but subordination remains a fact-sensitive remedy rather than an automatic penalty for being related to the debtor. The United States also recognises, through case law, the conceptually distinct inquiry whether an instrument described as debt should instead be treated as equity.
Singapore has adopted neither doctrine as a general free-standing jurisdiction. Section 6(1) of the IRDA provides that, subject to the Act, the court when exercising its jurisdiction under the Act has full power to decide all questions of priorities and all other questions of law or fact arising in any case or matter under the Act coming within its cognizance, or that it considers expedient or necessary to decide for the purpose of doing complete justice or making a complete distribution of property. By section 3, that court is the General Division of the High Court. In a voluntary winding up, section 181 allows the liquidator or any creditor or contributory to apply to the court to determine any question arising in the winding up, or to exercise any power the court might exercise in a winding up by the court.
Those words are tantalising. Yet section 6(1) begins with the qualification “subject to this Act”, and speaks to the exercise of a jurisdiction the Act confers. A general supervisory and procedural jurisdiction is not obviously a licence to create a new substantive priority that Parliament did not enact.
If Singapore is to recognise these remedies, legislative intervention would provide greater legitimacy and predictability than asking courts to construct them from general statutory language.
The strongest case against reform
There is substantial force in the orthodox position.
First, external creditors can inspect a company’s filed accounts. If the balance sheet discloses minimal share capital and substantial shareholder loans, a commercial creditor may price that capital structure into its decision. Insolvency law should be slow to rewrite disclosed bargains after failure merely because the outcome attracts sympathy.
That answer is less satisfactory for retail consumers, who neither conduct solvency analysis nor negotiate credit terms, but it remains powerful for banks, landlords and sophisticated suppliers.
Second, shareholder loans are often rescue financing. A founder may inject cash urgently to make payroll, preserve operations or complete a turnaround. A blanket rule that shareholder debt ranks last would punish the person who attempted to save the business and deter future rescues. Singapore’s policy has in fact run the other way: section 67 of the IRDA allows the court to confer super priority on rescue financing in a scheme context.
Third, recharacterisation creates hindsight risk. Almost every unsuccessful investment looks like risk capital after insolvency. Courts would have to reconstruct the parties’ reasonable expectations when the money was advanced, not impose equity retrospectively merely because repayment ultimately became impossible.
Fourth, uncertainty itself has a cost. Corporate groups routinely move liquidity among subsidiaries. If priority depends upon an open-ended judicial assessment of fairness, intra-group financing may become more expensive, slower and harder to document. The price of protecting external creditors could be reduced willingness to fund viable but temporarily distressed companies.
Fifth, subordination is redistributive. It does not create new assets. It improves one creditor’s recovery by reducing another’s. Compelling hardship suffered by consumers does not, without more, explain why their claims should prevail over landlords, suppliers, tort claimants or other involuntary creditors.
These objections defeat any crude proposition that shareholder debt should automatically rank below external debt. They do not necessarily justify the opposite extreme: that a court should never be permitted to examine whether insider financing lacked the commercial substance of debt.
A possible statutory framework
If Parliament revisits the issue, the safer reform is not a categorical rule. It is a narrow jurisdiction exercised on evidence.
The IRDA could empower the General Division of the High Court, on the application of a liquidator, to:
- recharacterise all or part of shareholder or related-party financing as a capital contribution where its commercial substance was risk capital rather than genuine credit; or
- subordinate genuine insider debt, to the extent necessary, where inequitable conduct connected to the claim or its enforcement caused unfair prejudice to external creditors.
The liquidator should be the principal gatekeeper. The liquidator represents the collective estate, possesses access to company records and is better placed than individual creditors to investigate the financing history. A creditor might be permitted to apply with leave where a liquidator unreasonably refuses to act.
No single factor should be decisive. The court could consider:
- whether there was a genuine fixed maturity;
- whether interest was commercially explicable, accrued and paid;
- whether repayments occurred in accordance with the terms while the company was solvent;
- whether security, covenants or ordinary lender protections existed;
- whether an independent financier would plausibly have lent on comparable terms;
- whether repayment depended substantially upon the success of the business;
- whether the company was materially undercapitalised when the advance was made;
- whether the funds became permanent working capital;
- whether the lender exercised control inconsistent with an arm’s-length creditor relationship;
- whether advances were proportionate to shareholdings;
- how the parties contemporaneously documented and accounted for the advance; and
- whether a genuine expectation of repayment existed at inception.
The burden should initially rest upon the liquidator to establish a prima facie case from objective evidence. Only then should the evidential burden shift to the insider, who possesses the relevant documents and knowledge, to explain the commercial basis of the transaction. That allocation is not novel: the unfair preference regime already presumes a desire to prefer where the counterparty is connected with the company, and leaves the connected party to rebut it.
The court should also be able to reach a partial result. One facility may comprise HK$50 million of genuine emergency rescue funding and HK$200 million of permanent quasi-capital. An all-or-nothing classification could be as artificial as the label it seeks to correct.
Most importantly, legislation should contain a safe harbour. An advance should not be recharacterised solely because it was made when the company was distressed or insolvent. Properly documented, commercially reasonable and bona fide rescue financing should be protected, not discouraged.
The resulting hierarchy would distinguish:
- genuine arm’s-length or commercially grounded insider debt, ranking ordinarily;
- genuine insider debt subordinated in exceptional circumstances because of inequitable conduct; and
- purported debt that was substantively risk capital, treated as equity.
Should consumer prepayments receive priority instead?
A different response would be to give some consumer prepayments a limited statutory preference.
There is intuitive appeal. Until services are supplied, a customer has effectively provided the business with interest-free unsecured funding. Unlike an informed lender, the customer receives no return for bearing insolvency risk and may not know that the risk exists. A lifetime membership illustrates the unusual duration of that exposure: even after more than a decade of use, the customer remained dependent upon the operator’s continuing solvency for the balance of the promised entitlement.
But every statutory preference dilutes the recovery of creditors outside it, including the employees who already sit near the front of the queue under section 203. Why should a gym customer rank above a small supplier whose unpaid invoices threaten its own survival? What about a tenant’s deposit, a student’s prepaid tuition fees, an unused beauty package or damages owed to an involuntary tort creditor? Drawing the boundary is difficult, and aggressive priority might raise costs or reduce access to prepaid services.
Consumer protection may therefore be better addressed partly before insolvency: limits on the duration or value of advance packages, segregation or trust arrangements, compulsory insurance, staged billing, clear risk disclosure, or stronger chargeback mechanisms. Those interventions reduce the exposure rather than redistributing a depleted estate after collapse.
This does not make consumer priority irrelevant. It shows only that insider-debt scrutiny and consumer protection solve different problems. One asks whether a controller’s claim belongs in the ordinary pool. The other asks whether consumers should enter that pool at all.
What True Fitness actually proves
True Fitness does not prove that the Kontafarma group’s claim should be subordinated, nor that Singapore’s insolvency priorities are wrong. Publicly available information does not reveal enough about the parent financing to determine its legal or economic character. The winding ups have barely begun, proofs of debt have not been adjudicated, and reported aggregate assets are not a proxy for funds available for distribution.
What the collapse does furnish is an unusually stark case study. The reported parent-group balance was nearly half of total liabilities. On one side are customers who prepaid for future services without control, material financial information or any ability to structure the operator’s funding. On the other is a controller-linked creditor whose relationship with the debtor is, by its nature, potentially accompanied by superior information and structuring power.
If both claims are genuine unsecured debts, pari passu supplies a formally coherent answer: equal claims share equally. But formal equality does not eliminate the antecedent question of classification.
Where a controlling shareholder sustains an undercapitalised subsidiary principally through related-party loans rather than equity, should insolvency law invariably respect that choice? Or should the court have a carefully confined jurisdiction, on a liquidator’s application, to identify financing that was debt in name but equity in substance, and to subordinate genuine debt where control was used inequitably to prejudice outsiders? The competing risk is real: such powers may introduce more uncertainty, hindsight and cost than the injustice they seek to cure.
Perhaps the orthodox answer remains the correct one. But when a customer who thought she was buying exercise classes may stand in the same insolvency queue as a controlling group’s HK$309.7 million financing claim, it is worth asking whether equality in the waterfall has been built upon an assumption of equivalence that the economics do not support.
True Fitness may therefore be more than another cautionary tale about prepaid packages. It may be an appropriate occasion for Singapore to ask a harder question:
If control and information have economic value everywhere else in corporate finance, should they remain categorically irrelevant when insolvency law decides who bears the loss?
Sources
- Kontafarma China Holdings Limited, HKEX announcement dated 10 September 2026 concerning the proposed creditors’ voluntary winding up of True Fitness Pte. Ltd. and True Yoga Pte. Ltd.
- Channel NewsAsia, reporting on the closure and on CASE complaint figures, 11 September 2026.
- Consumers Association of Singapore, statements by President Melvin Yong, 11 September 2026.
- Mothership, reporting of Shin Min Daily News interviews with affected “Lifetime Founder VIP” members, September 2026.
- Bloomberg, reporting on the provisional liquidation and accumulated losses of the two companies, 11 September 2026.
- Lim Oon Kuin and others v Ocean Tankers (Pte) Ltd (interim judicial managers appointed) [2021] SGCA 100; [2022] 1 SLR 434, especially at [28].
- Kon Yin Tong and another v Leow Boon Cher and others [2011] SGHC 228 at [39]–[40].
- Chee Yoh Chuang and another (as Liquidators of Progen Engineering Pte Ltd (in liquidation)) v Progen Holdings Ltd [2010] SGCA 31; [2010] 4 SLR 1089, especially at [3], [22]–[25] and [40]–[46].
- BCBC Singapore Pte Ltd and another v PT Bayan Resources TBK and another [2023] SGCA(I) 1.
- DGJ v Ocean Tankers (Pte) Ltd (in liquidation) and another appeal [2024] SGCA 57; [2024] 2 SLR 790.
- Insolvency, Restructuring and Dissolution Act 2018, ss 3, 6, 67, 121(1)(g), 161, 172, 181, 203, 225(5) and Part 9.
- United States Bankruptcy Code, 11 USC §510(c).
The author is a corporate governance and valuation practitioner and writes here in a personal and academic capacity. This article is commentary on a developing matter of public interest and law reform. It is not legal advice, is not a substitute for advice on any specific situation, and should not be relied upon as such. Figures attributed to the True Singapore Group are unaudited aggregate management figures reported by its listed parent and may change on adjudication. The analysis of individual entity positions, recovery outcomes and the proper characterisation of any financing is necessarily provisional. Nothing in this article alleges impropriety by the parent, the directors, the operating companies, their advisers or the provisional liquidators, or expresses any conclusion on the admission, quantum or ranking of any proof of debt.



Leave a Comment
Your email address will not be published. Required fields are marked with *